
Or paid is the wrong first question for a budget planner. The right first question is: which income number is the planner planning around? If it is the headline stipend on your offer letter, the plan is built on a number you never actually get to spend. The honest input is the cost of living adjusted phd stipend, and once you see how far the adjustment moves real offers, the versus paid debate gets much smaller.
What a cost of living adjusted phd stipend actually looks like
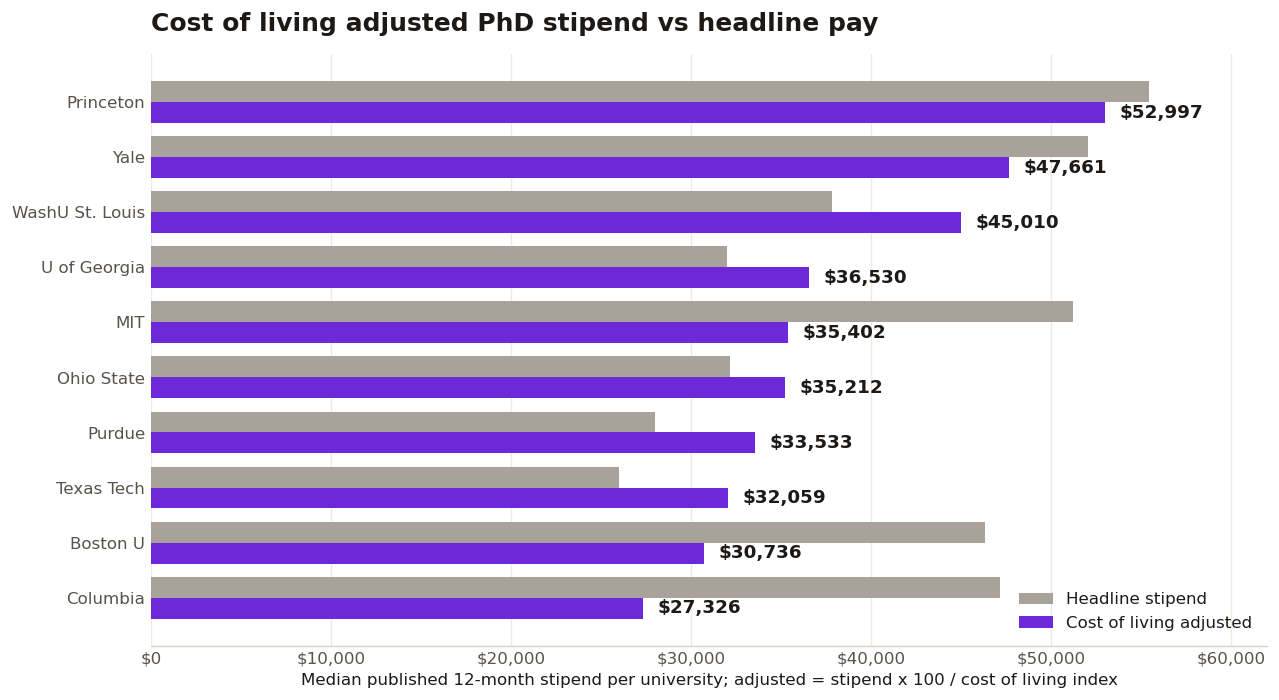
Start with the flip that surprises everyone. Columbia's median published stipend is $47,137, one of the highest on this page. Adjusted for New York costs (index 172.5), it is worth $27,326. Texas Tech pays a modest $26,000 in Lubbock (index 81.1), which adjusts to $32,059. The offer that pays $21,137 less on paper is worth about $4,700 more in real terms. A planner fed the headline numbers would rank these two offers exactly backwards.
The pattern repeats across the chart. Washington University in St. Louis turns $37,853 into $45,010 of purchasing power. Purdue turns $28,000 into $33,533, and Ohio State turns $32,184 into $35,212. At the expensive end, MIT's $51,226 shrinks to $35,402 and Boston University's $46,350 shrinks to $30,736. Princeton is the rare place where both numbers are big: a $55,435 headline adjusts to $52,997, because its index is a mild 104.6. Across all universities with published 12 month stipends, the median headline of $37,818 becomes $34,482 after adjustment.
So the planner's job is not really to track coffee. It is to hold you to a monthly plan built on the adjusted figure, which for most students is several hundred dollars a month below the number in the offer letter.
Budget planner apps: the compared verdict

With that settled, the original verdict stands. planners cover the core: EveryDollar's basic tier, Goodbudget's envelopes, and a plain spreadsheet cost you nothing and handle stipend budgeting fine. If your adjusted number is tight, stop there. The savings from a paid planner cannot compete with picking the right offer.
Worth paying for, in the cases where they fit: YNAB, if you need the method enforced; the subscription pays for itself when it prevents one overdraft spiral. Copilot, if beautiful iOS design is what gets you to open the app weekly. Not worth paying for: premium tiers that add investment tracking you do not need yet, and any planner with a subscription you will cancel in month two. The rule we keep coming back to is simple: pay for tools that change the big decisions, which offer and what rent; use tools for the small ones, daily spending.
One habit matters more than the tier: refresh the budget numbers weekly, and keep research spending in its own category, separate from personal spending. Mixing them hides both patterns, and reimbursements get lost.
A monthly plan built on the adjusted number
Here is what planning on the adjusted figure looks like in practice. Take the median adjusted stipend across universities, $34,482 a year. That is $2,874 a month of real purchasing power, and a planner built on it might set rent at $1,150 (splitting a place, since the median program in our data would need 54 percent of its stipend for a solo one bedroom), food at $500, transport at $160, and a combined $250 for phone, subscriptions and course costs. That leaves roughly $800 a month for savings, travel home, and the irregular expenses that wreck first year budgets: deposits, winter clothes, a dead laptop.
Build the same plan on the unadjusted $37,818 headline and every category quietly inflates by about $280 a month in total. Nothing feels wrong in September. By November the plan is overdrawn and the student concludes they are bad at budgeting, when in fact the plan was written against income that never existed. This is the single most common budgeting failure we see in the stipend data, and no premium tier fixes it. The input number has to be right first.
Plan around your adjusted number
Before you pick a planner, get your adjusted figure. TheRealTerms Calculator runs your stipend against rent and cost of living for your city and shows what is actually left each month. Build the planner around that leftover. For more on the adjustment itself, read the cost of living ranking and our roundup of stipend calculator tools.